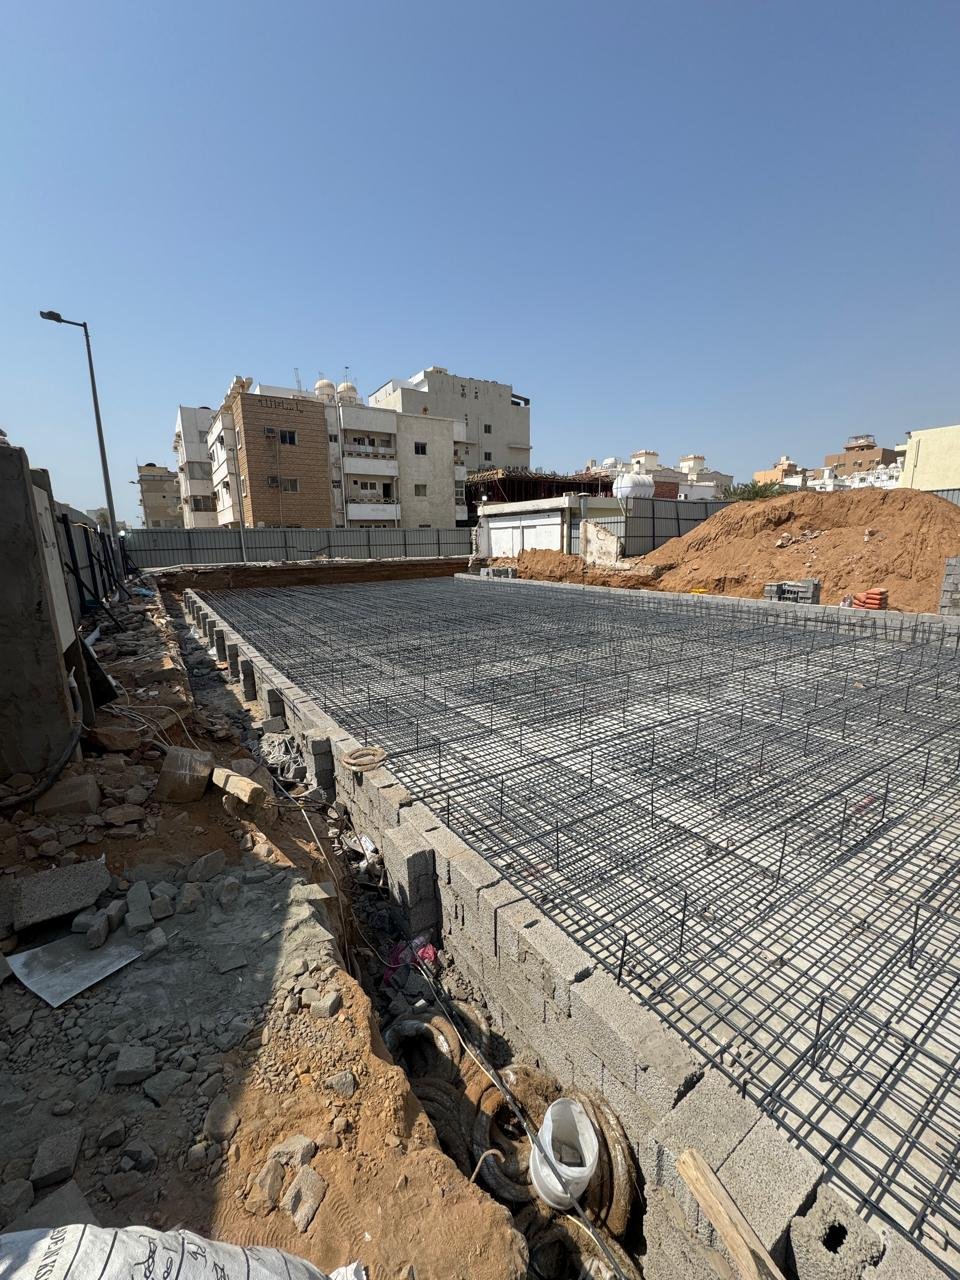
A Site Is Priced Twice: What the Advisor Reads Before Acquisition
Long before the first line is drawn on paper, the land has already spoken. Yet most major real-estate decisions are made on what a site shows: its frontage, the area recorded on the deed, its proximity to services. That is the market reading, and it is both correct and incomplete. An advisor is not paid to see what the market sees. An advisor is paid to see what it does not, and to price that before it becomes a surprise in the budget.
Site appraisal before acquisition is neither a design study nor a memorable walk across the ground. It is an investment judgment that precedes the architect rather than follows him: can this land carry the asset we intend, and return the capital we will bury in it? The question is economic before it is aesthetic, and its answer decides whether there is a project at all.
Site Analysis Is Not Site Appraisal
There is a long tradition of reading a site for design, whose rules Kevin Lynch and Gary Hack set out in Site Planning (MIT Press): solar orientation, wind, levels, views, routes of approach. That reading asks a single question, how do we place the building on the land? Appraisal before acquisition asks an earlier and graver one, do we buy this land at all, and at what price? The first is a spatial reading led by the designer, and we traced its logic in Reading a Site: What Models Calculate and Architects Decide. The second is an investment reading led by the advisor, and it begins where the field visit documented in Before the First Line: Two Site Visits to Riyadh leaves off. Confusing the two is expensive: there are sites that are beautiful to design and ruinous to own, and the reverse holds just as often.
Highest and Best Use Governs Value, Not the Buyer’s Intention
Land is valued not by what the buyer intends to build, but by the highest use the land both permits and can bear. In The Appraisal of Real Estate, the Appraisal Institute compresses this principle into four sequential tests: a use must be legally permissible, then physically possible, then financially feasible, and finally the most productive among those that survived the first three. The order is not a formality. A use the owner dreams of may fall at the first gate because zoning forbids it, or at the second because the soil cannot carry it economically. This is precisely where the price of illusion is paid: when a site is valued on a use that will never be licensed, or a density that will never be approved, the buyer pays today for value that will not arrive tomorrow. The disciplined valuer prices the land on its established highest and best use, not on its owner’s wish.
What Lies Below the Surface Gets Priced, or Prices Itself
A site’s largest risks are its least visible. What sits below grade, the bearing capacity of the soil, the groundwater table, swelling clays, voids, decides much of the foundation cost that can consume the margin before the building rises a single metre. Eurocode 7 (EN 1997) for geotechnical design and ISO 22475 for geotechnical sampling govern the method of boring and testing, but the economic lesson was stated most plainly by the Site Investigation Steering Group of the Institution of Civil Engineers in its series Site Investigation in Construction: the cost of sound geotechnical investigation is a slender fraction of project cost, while poor ground is among the most common causes of cost and time overrun. The exact proportion is debated across the studies and varies with project type and ground, yet the direction of the relationship does not change. Ignorance of what lies below is not cancelled by deferring it; its price is merely postponed until it grows larger. The advisor who recommends boring before the bid usually saves a multiple of what it costs.
Layers of Constraint and the Genuinely Buildable Envelope
When each constraint is drawn on its own and stacked over the one before it, the true map of the site appears. The method was established by Ian McHarg in Design with Nature (1969), where he overlaid transparent maps for every factor: slope, drainage, soil capacity, flood zones, statutory setbacks, utility easements. What remains white after the layers are stacked is the genuinely buildable envelope, and on many sites it is far smaller than the deeded area. A buyer who prices land by the raw square metre is buying an illusion; the advisor prices it by the developable square metre, after subtracting what cannot be built upon. The gap between those two numbers is the same gap that separates a profitable deal from one that merely looks profitable.
The Residual Method: What the Land Can Afford to Pay
How is all of this translated into a number to put on the negotiating table? Through the residual method of valuation, codified for development land in the RICS Valuation Global Standards, the Red Book: estimate the gross development value of the finished scheme, then subtract construction cost, fees, finance, and the developer’s required profit; what remains is the most the land can afford to pay without the project losing money. This is not an arithmetic trick but an inversion of logic. The price is not derived from what the seller paid or what he asks, but from what the scheme itself permits. When the asking price exceeds that ceiling, the site is not merely expensive; it is undevelopable at prevailing prices, which is an entirely different verdict from a haggle over the figure.
The Constraints That Do Not Appear in the Aerial Image
One layer remains that neither the aerial image nor the borehole captures: rights. Easements, rights of way, mortgages, title restrictions, the capacity of utilities that is actually available rather than assumed, and any live boundary dispute. Due diligence is the methodical survey of this layer, and it is what turns land that looks vacant into a file of known risk before the contract is signed. A site crossed by a public service, or lacking a legal access to the road, or bounded by a neighbour’s rights, can lose half its value in a single line of the title register. The advisor does not read the ground alone; he reads its documents, because value that no legal instrument protects is value on loan.
Land Does Not Lie, but It Does Not Volunteer the Truth
What these layers share is that none of them shows up in a passing visit or a sales listing. The market prices what is seen; the advisor prices what can be inferred. That is why appraisal precedes the decision, and the decision precedes the first line. A building raised on a mispriced site goes on paying for that error across its entire operating life, however accomplished its design. Land does not lie, but it does not volunteer the truth; the advisor’s task is to extract it before it is paid for.
Sources: Kevin Lynch and Gary Hack, Site Planning (MIT Press); Ian McHarg, Design with Nature (1969); Appraisal Institute, The Appraisal of Real Estate, the four tests of highest and best use; Royal Institution of Chartered Surveyors, RICS Valuation Global Standards (the Red Book), residual method for development land; Site Investigation Steering Group, Institution of Civil Engineers, Site Investigation in Construction; Eurocode 7 (EN 1997) for geotechnical design and ISO 22475 for geotechnical sampling.